Fast Car Finance Australia Wide
We help Aussies get the best car finance deals. Whether you’re looking for a new, used, luxury, or utility vehicle our team of brokers will ensure you get the funding you need.
- 63+ lenders
- Priority service
- 24 hour turnaround
- Funding as fast as 8 hours
- No doc and low doc available
- Financing hundreds of vehicles
Excellent reviews from Aussie businesses
A quick guide to fast car finance
Car finance is easily the most common type of finance across Australia. From the Ford Ranger to the Toyota Hiace both businesses and individuals need vehicles to move around. Every car finance solution we offer is tailored to match your specific needs, requirements, and financial circumstances. Here’s an overview of our car finance options. Please note that terms and rates may vary at the time of application based on market conditions, crop cycles, and individual assessments.
Typical Loan Details
- 7yr Loan Terms Available
- 63+ lenders available
- Weekly, fortnightly, or monthly repayments
- Early repayments options
- Balloon payment options
- Borrow up to $500,000 with a low doc loan
- No deposit (even for non home owner)
- Equipment across all industries in Australia
Calculate your estimated car loan repayments today
Feel free to estimate your rate, term, and deposit to get an idea of how much your repayments might be. Please keep in mind this is only to get a general idea and is not the calculator we will use to determine your actual loan repayments.
$
6.99%
5 years
$495
$29,695
Fast Car loans Australia-wide
We believe securing the right vehicle is a big deal.
There are many options for you to source, negotiate, and finance your car.
Our job is to cut through the noise, find you the right options, and close a deal quickly.
We work with businesses and individuals across Sydney, Canberra, Melbourne, and Queensland.
Whether you’re a tradie expanding your fleet, a transport company signing new routes, or someone who just wants a new car, we’re here to make it happen.
Our team understands how important it is to ensure you get the best service possible, access to the right finance, and support throughout the whole process.
Unlike a home loan or personal loan, your access to car finance will determine how fast you can get on the road.
Get in touch with our team today so we can guide you through the process and find the best deal on your vehicle loan.
And if you haven’t found your car yet, our team can help source it a cheaper price.
Your options at a glance
Finance structures compared
| Structure | Ownership | Tax treatment | Balloon | Best for |
|---|---|---|---|---|
| Chattel mortgage | You own the asset from day one; the lender holds a mortgage over it as security. | GST, depreciation and interest are generally deductible. Speak to your accountant. | Available | Businesses that want to own the asset from the start. |
| Finance lease | The lender owns the asset during the term; you have full use of it. | Payments may be deductible depending on your circumstances and business use. Speak to your accountant. | Residual payment to take ownership | Businesses that want to use the asset now and buy it at the end. |
| Commercial hire purchase | The lender owns the asset during the term; ownership transfers to you at the end. | GST, interest and depreciation are generally deductible. Speak to your accountant. | Available (final instalment) | Businesses that want to own the asset later, paid off in instalments. |
| Operating / rental lease | You never own the asset. You use it and return it at the end. | Payments may be deductible as an operating expense. Speak to your accountant. | Not applicable (you return the asset) | Short-term needs, or businesses that upgrade equipment often. |
What we need from you
| Item | Why we need it |
|---|---|
| Your name and contact details | So we can reach you and talk through the right option for your business. |
| Your ABN | So we can confirm you're financing through the business and match you with commercial lenders. |
| The asset type and price range | So we know which lenders actually fund that asset, and whether it's a no doc, low doc, or full doc application. |
| Whether you have a deposit, and when you need the asset | So we can structure the repayments around your cash flow and the date you need it. |
Get in touch with our team of Asset Finance Brokers today.
You can book a free discovery call with our team to learn about your options or simply submit an enquiry and we’ll call you back as soon as possible.
What are the pros and cons of a car loan?
Cons
- Higher monthly repayments
- Typically costs more than paying cash upfront
- Responsible for maintenance costs
- Requires comprehensive insurance coverage
- Requires a good credit history for a good rate
- Insurance costs can be slightly higher
- Risk of negative equity if the equipment value drops
- Easy to overcommit to new business
Pros
- Drive a new car without paying for it upfront
- No deposit required (even for non-home owners)
- Tax benefits (GST, depreciation, interest, etc)
- Access to a wider range of vehicles that you may not afford outright
- Possible balloon payment option to lower repayments
- Flexibility to upgrade to newer models at the end of some agreements
- Easier to forecast business growth and requirements
- Competitive rates and speed through broker relationships
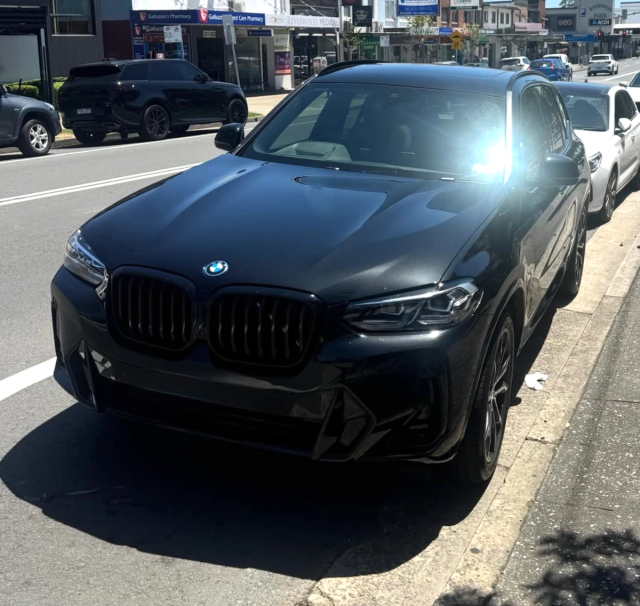
Real Estate Agent
- BMW X3
- Private sale, needed a fast turnaround
- Sharp rate and a quick settlement
A real estate agent buying a BMW X3 through a private sale, needing it done quickly. We pushed the process along and got it settled faster than a private sale normally moves.
Private sales don’t have to be slow.
Our process
Learn about you
We offer discovery calls to learn about your car finance finance requirements.
Compare car loans
We’ll shortlist the best options for you or your business and explain them to you.
Get pre-approved
We’ll secure pre-approval based on steps 1 and 2 so you have peace of mind.
Secure your car
Found the car? We’ll make sure you’re approved and the funds are available.
Why choose Stacked Finance?
Australia Wide
Our core team is based in Sydney. However, we support businesses all over Australia including Melbourne, Brisbane, Perth, Adelaide, Gold Coast, Canberra, and Newcastle.
Trustworthy
We believe integrity is the most important quality of a broker. Our team is honest and transparent about the options, fees, rates, timelines, and anything else you need to know.
24/7 Support
We’re committed to helping our clients. This means being available when they are. Most of our clients are busy running their companies – we ensure we’re available to support you when you need it most.
Let's talk loan details
- Up to $500,000
- Secured and unsecured
- 3, 5, and 7 years (depending on the age of the asset)
- Weekly, fortnightly, and monthly
- Fixed
- No deposit available up to $150,000, subject to your profile and the asset
- Generally up to 25 years at the end of the loan term
Some of our lenders on panel (we have access to 63+ lenders)
Book a free 20-minute discovery call
Not sure where to start? Feel free to book a call with our team to chat through your objectives. On the call, we’ll talk you through your business goals, asset requirements, processes, expected timelines, and anything else to help you make an informed decision.
What you’ll need to apply
Have these to hand and the application takes a couple of minutes.
- Your name
- Phone number
- Email address
- Your ABN
- The type of asset you are financing
- The price range you are looking at
- Whether you have a deposit
- When you need the asset, and how soon
What happens next
We read your application
We look at the asset, the amount and your business details.
We compare lenders
We shortlist the options that fit and explain them to you.
We come back to you
We talk you through what you can do and what it would cost.
You decide
Nothing moves forward until you say so.
Frequently Asked Questions
What is car finance?
Car finance helps both individuals and businesses purchase a vehicle without paying the full amount upfront. Buyers can access the cash they need immediately for both new and used cars and slowly pay the loan off over the agreed term with interest. Whether you’re looking to buy your first car, upgrade, or add vehicles to your fleet, the team at Stacked Finance is here to support you.
Can you source cars at a better rate?
Yes – we also help our clients source cars at a cheaper rate than they can normally access through a dealership.
Which car finance terms should I know?
When it comes to car finance (or any asset finance in general) there are many terms to learn. Each of them is important in its own way and to some degree is essential if you plan on getting a car loan. You want to be informed and able to make the best decision possible with the information you have.
Here are the top terms we suggest getting your head around:
- Chattel mortgage – A loan that is secured by the asset you purchase.
- Operating lease – An arrangement where you rent the equipment but don’t own it.
- Finance lease – Where you can lease the asset with the option to purchase at the end of the term.
- Commercial hire purchase – Pay for the asset in installments and own it later.
- No doc loan – Close to zero financial documentation is required for this loan.
- Low doc loan – Minimal paperwork for getting a loan.
- Full doc loan – Detailed financials are required by lenders to access better terms.
- Residual value – The estimated worth of your asset after it has fully depreciated.
- Balloon payment – A large payment at the end of the loan term.
- Comparison rate – Interest rate including fees and charges relating to a loan (the “real” interest rate).
- Establishment fee – A loan creation fee paid to the lender.
- Secured car loan – The car is used as collateral for the loan.
- Unsecured loan – There is no security tied to the loan.
- Offer of credit – When lenders offer formal pre-approval.
- Depreciation benefits – Tax deductions for the asset use.
- Loan Principal – The original amount borrowed.
- Credit Score – Your rating of financial trustworthiness by credit companies.
- Lender Criteria – The lender rules to qualify for finance.
- GST – 10% tax applied to the purchase price.
- Tax deductibility – Your claimable expenses for financing.
- Asset turnover ratio – The measure of revenue from assets.
- Credit assessment – The lender’s evaluation of your borrowing capacity.
- Fixed interest rate – The fixed interest rate that does not fluctuate with the market.
- Variable interest rate – The interest rate that fluctuates with the market.
- Broker fee – Our fee for arranging the finance deal.
- Early termination fee – A penalty for paying off your loan early.
- Bank statements – your bank transactions to confirm you can afford the repayments.
But don’t worry! There’s no need to remember all of this.
Our team of asset finance brokers is here to make this process quick, simple, and easy for you.
Am I eligible for car finance?
Most Australians and Australian businesses are eligible for car finance!
The requirements differ between individuals and businesses though. Here’s what to know
For individuals:
- Be at least 18 years old with a valid Australian driver’s license
- Have a regular source of income (full-time, part-time, casual, or self-employed)
- Be an Australian citizen, permanent resident, or hold a valid long-term visa (depends on the lender)
- Have a reasonable credit history (options available for those with bad credit)
- Demonstrate the ability to make repayments within your budget
- Provide identification documents (e.g., passport, driver’s license, Medicare card)
- Supply proof of income (recent payslips, tax returns, or bank statements)
- Show proof of address (utility bills or official correspondence)
For businesses:
- Have an active ABN (over 2 years is best but not required)
- Be GST registered (over 2 years is best but not required)
- Be operating for at least 6-12 months (some lenders may finance newer businesses)
- Demonstrate consistent business revenue and cash flow
- Provide business bank statements for the last 3-6 months
- Supply financial statements (profit and loss, balance sheet)
- Have a reasonable business credit profile
- Directors may need to provide personal guarantees
- Vehicle must be primarily for business use (for business-specific finance options)
Note: If you want a quick business loan then you likely will not need to provide all of this information. A low-doc loan will allow you to secure a car loan without much documentation.
Which types of vehicles can I finance with Stacked Finance?
For individuals, no type of car is off-limits. However, there are a few considerations:
- The car must be road-worthy and registered
- You may receive discounted rates for electric vehicles (EVs)
- Your income and expenses will impact how much you can borrow
- Your credit score will impact whether you’re eligible and at what rate
- The car must have some resale value
For businesses, the golden rule is simple: cars must serve a clear business purpose.
While that sounds straightforward, lenders have specific criteria about what qualifies.
They’re looking at the asset’s potential to generate value for your business.
In addition, most lenders have stringent policies about the types of assets they’ll finance based on resale value. These are usually categorised as primary, secondary, or tertiary (in some cases category A, B, or C).
- Primary assets: These are assets with the highest resale value and are the easiest to sell. These usually include cars, trucks, trailers, excavators, heavy machinery, and other earth-moving equipment. These assets carry the most attractive rates and terms.
- Secondary assets: These typically include medical equipment, food, and manufacturing equipment. They have a resale value but are not as easy to sell as a new car. These assets have slightly less attractive rates and terms since they have less value.
- Tertiary assets: These assets have little to no value in the marketplace and are not easy to sell. They can include things like a 25-year-old trailer or a POS system. Tertiary assets carry much higher interest rates and less favourable terms since they are a major risk for the lender to finance.
The key is that the car or vehicle needs to be for genuine business use. Most lenders will work with you to understand how the asset fits into your operation and structure the finance accordingly.
What’s the difference between a secured and unsecured car loan?
This is one of the most common questions we get at Stacked Finance.
To put it simply a secured car loan means the asset (i.e. your car) serves as security to the lender. If you miss repayments or default on your loan the lender can repossess your vehicle. The interest rate is usually lower on secured car loans since there’s less risk to the lender.
Unsecured car loans on the other hand are not secured by anything. This means if you default on your loan the lender can not automatically repossess your car. They still have every right to pursue legal action though. The interest rates are typically higher on unsecured car loans.
How can I get the lowest repayments for my car loan?
Reducing your car repayments comes down to a few core factors. Here’s what we recommend to our clients to keep costs low:
Loan term strategies
- Extend the loan term (more months = smaller repayments)
- Balance term length against total interest paid
- Consider 5-7 year terms for optimal flexibility
- Consider getting a lower model to save costs
Deposit & upfront payment
- A larger initial deposit will always reduce the principal & result in less interest
- Lower borrowing amount means smaller monthly repayments
- Aim for 20-30% deposit if possible since you’ll also access lower rates (lenders like deposits – but it’s not essential)
Additional Tactics
- Choose a car with a strong resale value (check out which vehicles are most popular)
- Negotiate car pricing before financing or work with our team to source your car
- Consider residual payment structures (i.e. balloon payments)
- Compare multiple lender options
- Consider a full-documentation loan to access a better rate
Pro Tip: Don’t just chase the lowest repayment. The cheapest option isn’t always the most cost-effective long-term. A slightly higher repayment might save you thousands in total interest.
Our car finance brokers will crunch the numbers and find a sweet spot between lower monthly repayments and overall loan cost.
What should I look out for in a car loan broker?
When choosing a car finance broker in Australia, you’ll need to be aware of some essentials.
Firstly, all brokers should be FBAA or MFAA-accredited brokers (this means they are backed by an Australian Credit Licence). Secondly, they should also have the relevant qualifications and industry experience.
On top of this, a good broker should:
- Have close relationships with multiple lenders, not just their preferred lenders (we have 63+ to choose from and we deeply understand their lending criteria)
- Take the time to understand your personal circumstances, business goals, and car requirements
- Be upfront about all rates, fees, processes, repayment terms and charges
- Know the ins and outs of different finance structures (e.g. chattel mortgage vs commercial lease)
- Work with your financial situation to ensure you actually get approved
- Understand the tax implications for your business of each loan structure
- Fights to get you the best deal possible and conditional approval ASAP
- Understand the current ATO position on tax deductions and other related initiatives (if not then proactively seek the right tax advice for you)
Most importantly, they should speak your language – if the broker can’t explain how the loan works without using fancy jargon, keep looking. At Stacked Finance we provide professional advice in plain english without the jargon, we want you to be informed and stay in control of your finances.
What other services do you offer?
Stacked Finance is focused on the commercial market as opposed to consumer.
This means we only help Australian businesses obtain equipment loans or business loans.
Whether you need a new asset like a truck, ute, tractor, or digger, we can help. Our team is also skilled at providing working capital loans, cash flow finance, unsecured loans, startup loans, or any other specific type of business-related funding.
Need help with finance?
Send Emmanuel a message and he’ll get back to you shortly.
Or call Emmanuel directly on 0417 209 702