Stacked Finance

Sydney Truck Finance Experts

Most Sydney operators find their truck somewhere else. We finance trucks bought interstate, regionally and privately, and we get the asset checked before you commit.

  • 63+ lenders
  • Based in Sydney
  • 24 hour turnaround
  • Funding as fast as 8 hours
  • No doc and low doc available

Get a free quote

Step 1 of 2 — Personal Details

Personal details
Your asset and amount
Roughly how much?

Here is the thing about buying a truck in Sydney.

The truck usually isn't in Sydney.

More than half the Sydney deals we place involve a truck outside Sydney: roughly a third interstate and another third in regional New South Wales. A box truck in Newcastle. A truck from a seller outside Canberra. An unregistered agitator from a private seller, right at the edge of what lenders will look at.

Sydney has more buyers than it has trucks, so Sydney operators look further out. That is a sensible thing to do. It is also where finance gets complicated, because now you are dealing with a private seller you have never met, an asset you have not stood next to, and a registration that has to end up valid in New South Wales.

That is the part we handle.

Can we finance a truck that isn't in Sydney?

Yes, and we do it constantly. Buying out of area is normal for Sydney operators and no lender treats it as unusual.

What changes is the verification. When the truck is four hours away, the lender still has to be satisfied it exists, that it is what the seller says it is, and that nobody else has a claim on it. Four things decide how smoothly that goes.

1. Where the truck is and who is selling it

A dealer sale interstate is close to a local one. The dealer has the paperwork, holds the asset and is used to settling with a lender.

A private sale is where the work is. We will need proof the seller owns the truck, its registration status, a payout figure if there is finance owing on it, photographs, a PPSR check and an inspection.

Before we go any further we also ask you four questions, because the answers predict whether the deal runs cleanly:

  • How are you getting the truck back to Sydney?
  • When?
  • Does the seller know the buyer is interstate?
  • Is the seller willing to work with us on the inspection?

That last one matters more than people expect. An interstate purchase is rarely the problem. A seller who will not cooperate is.

2. Registration, and what New South Wales will want

A truck bought in another state has to be registered here, and New South Wales sets the terms.

If the truck has a Gross Vehicle Mass over 4.5 tonnes it is a heavy vehicle, and registering it in New South Wales needs a Heavy Vehicle Authorised Inspection Scheme (HVAIS) report. Lighter vehicles, including utes and vans under that mass, need an Authorised Unregistered Vehicle Inspection (AUVIS) report, the one everybody calls a blue slip. Either way the report has to be recent: Service NSW requires the original, issued no more than 42 days before you lodge.

You will also need proof of your identity, proof of registration entitlement, the original number plates and a compulsory third party green slip before it can go on the road here. Duty may apply, though New South Wales recognises duty already paid in some states.

None of this stops a deal. It shapes the order you do things in, which is the point of talking to us before you commit rather than after.

3. How much documentation you want to provide

Speed and paperwork trade against each other, and you get to choose.

Full doc gives you the widest lender choice and the sharpest structure. You provide tax returns, financials, BAS and bank statements.

Low doc asks for far less and moves faster. It works best when you can put down a deposit or you are property backed. Without one of those two it gets harder.

No doc is the quickest path and leans almost entirely on your credit history and the strength of the asset.

If you are buying privately and out of area, pre-approval on a low doc application is often the difference between having the truck and watching someone else take it.

4. The loan structure

Four structures cover almost every truck we finance, and the right one depends on how you use the asset and how your accountant treats it.

Chattel mortgage. Your business owns the truck from day one and the lender holds a mortgage over it as security. The most common choice for owner operators and small fleets.

Commercial hire purchase. You make regular payments and ownership transfers to you at the end of the term.

Finance lease. You lease the truck across the term with the option to purchase at the end. Lease payments are generally treated as operating expenses.

Operating lease. The lender owns and maintains the truck and you hand it back at the end. It suits operators who upgrade regularly and want the asset off the balance sheet.

Tax treatment depends on your circumstances and your structure. The ATO's guidance on motor vehicle expenses is the right starting point and your accountant should have the final say.

How do you buy a truck you have never seen?

This is the question underneath every out of area purchase, and it is the one most brokers leave you to solve alone.

We have a network of mechanics we can send to physically inspect the truck before you commit, and you get their written report.

Not a video call with the seller. Not a folder of photos taken at a flattering angle. A qualified person standing next to the asset, looking at what you would look at if you were there, putting it in writing.

We have done this on real deals. It is the single most useful thing we offer a Sydney buyer looking at a truck in another state, because it turns "I think it's alright" into something you and the lender can both rely on. And it is one less thing for you to organise: our job is to take as much of this off your hands as we can.

The most common holdup is photographs

Not registration. Not the interstate part. Photographs.

Buyers send us a handful of blurry shots from one side of the truck and the lender cannot verify the asset from them. The deal stops there until better ones arrive, and chasing a private seller for photos is slow.

Lenders generally want clear images of the identifying plates, the engine number area, the body and chassis, the interior, the odometer and any damage. If you are going to see the truck, take too many photographs rather than too few. If you are not going to see it, this is exactly what the inspection solves.

The other thing that holds deals up is roadworthiness on older trucks. An older unit is more likely to need work before it will pass inspection, and that work has to happen before registration, which means before settlement. It is worth knowing that on the day you find the truck, not a fortnight later.

And if the truck is unregistered, that is not the end of the conversation. An unregistered truck cannot be driven away, but it can absolutely be pre-approved. We have structured deals exactly that way, with the pre-approval in place while registration was sorted out.
A guide to truck finance in Sydney

Sydney operators buy under time pressure. A contract lands, a truck goes down, or a good unit appears privately at a price that will not last the week. The finance conversation is worth having before you find the truck, not after, because pre-approval is what lets you move on something that is four hours away.

Typical Loan Details

  • Flexible payment options
  • 63+ lenders available
  • Weekly, fortnightly, or monthly repayments
  • Simple application process
  • Borrow up to $500,000
  • No deposit available up to $150,000, subject to your profile and the asset

Calculate your truck loan repayment estimate today

Feel free to plug in some rate, term, and deposit estimates to get an idea of how much your repayments might be. Please keep in mind this is only to get a general idea and is not the calculator we will use to determine your actual loan repayments.

$
6.99%
5 years

Monthly Repayment

$495

Total Cost of Loan

$29,695

Your figures above are attached to the message — no re-typing.

Estimate only — not a quote or an offer of finance.

Built for how Sydney operators actually buy

Sydney is a hard place to buy a truck and an easy place to need one.

The work is here. The contracts are here. The depots, the distribution centres and the councils putting jobs out to tender are all here. What is not here, often enough, is the right truck at the right price, which is why so many of our Sydney clients end up buying in Newcastle, elsewhere in regional New South Wales, over the border, or from a private seller a long way from the M7.

That creates a specific kind of pressure. You are trying to commit to an asset you have not inspected, from a seller you do not know, while the clock runs on a contract you have already won. Meanwhile the major banks will tell you they move quickly, and then ask you for three years of financials and take a fortnight to look at it.
We work in that gap, and we take as much of it off your hands as we can. We get the asset verified, including sending a mechanic from our network to look at it in person when that is what the deal needs. We know what New South Wales will require before the truck can be registered here, so the order of events is planned rather than discovered. We get you pre-approved so that when you tell a private seller you are ready, it is true.
Whether you are an owner driver buying your first rigid, a courier adding a box truck to service a new contract, or a small fleet replacing a prime mover, the job is the same. Make the asset safe to buy, then make the finance fit the business.

Sydney Truck Finance

Get in touch with our team of Asset Finance Brokers today.

You can book a free discovery call with our team to learn about your options or simply submit an enquiry and we’ll call you back as soon as possible.

incapost truck

Customer case study

Courier Business

Asset
2024 Isuzu Pantech
Situation
New delivery contract, truck needed fast, bought in Newcastle, dealer finance slow
Outcome
Approved in 24 hours at a sharper rate than the dealership

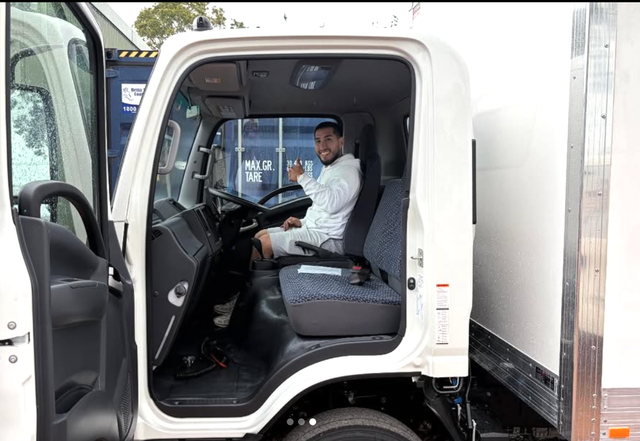
When Sydney courier company Inca Post signed a new delivery contract with an eBike business, they needed a box truck immediately to service the work and avoid missing revenue.

Dealership finance options were expensive and slow, so they came to Stacked Finance looking for a sharper rate, fast approval, and a structure that supported their cash flow.

We secured approval within 24 hours and negotiated a better rate than the dealership, giving Inca Post the confidence to deploy the truck straight away and begin delivering e-bikes across Sydney.

As they put it: “Emmanuel answered all our silly questions, settled our concerns, and made the entire process smooth and seamless, all while getting us a great deal.” – see the Google Review here.

Our process

Step 1

Learn about you

We offer discovery calls to learn about your business and truck finance requirements.

Step 2

Compare truck loans

We’ll shortlist the most favorable options for your truck and explain them to you.

Step 3

Get pre-approved

We’ll secure pre-approval based on steps 1 and 2 so you have peace of mind.

Step 4

Secure your truck

Found the truck? We’ll make sure you’re approved and the funds are available.

Why choose Stacked Finance?

Australia Wide

Our core team is based in Sydney. However, we support businesses all over Australia including Melbourne, Brisbane, Perth, Adelaide, Gold Coast, Canberra, and Newcastle.

Trustworthy

We believe integrity is the most important quality of a broker. Our team is honest and transparent about the options, fees, rates, timelines, and anything else you need to know.

24/7 Support

We’re committed to helping our clients. This means being available when they are. Most of our clients are busy running their companies – we ensure we’re available to support you when you need it most.

Let's talk loan details

Loan amounts
Up to $500,000
Loan type
Secured and unsecured
Loan terms
3, 5, and 7 years (depending on the age of the asset)
Repayments
Weekly, fortnightly, and monthly
Interest rate
Fixed
Deposit
No deposit available up to $150,000, subject to your profile and the asset
Asset age limit
Generally up to 25 years at the end of the loan term

We have access to 63+ lenders and we're adding more

  • Plenti
  • Banjo
  • Moneytech
  • Prospa
  • NAB
  • Now Finance
  • Latitude
  • Metro
  • Azora
  • Shift
  • Wisr
  • Firstmac
  • Lumi
  • ScotPac
  • Dynamoney
  • Moula
  • Money3
  • Angle Auto Finance
  • Westpac
  • RACV
  • Rapid Loans
  • Pepper Money
  • Resimac
  • Liberty
  • Orix
  • MoneyMe
  • FinanceOne
  • TruePillars
  • flexicommercial
  • CFI Finance
  • Multiply Finance
  • Carstart
  • Morris Finance
  • Affordable Car Loans
  • Alex Bank
  • Bizcap
  • BOQ Finance
  • Capital Finance
  • Earlypay
  • Maple
  • Branded Financial Services
  • Selfco Leasing
  • AFS Automotive Financial Services
  • Asset Rental Group
  • Quest Finance
  • And many more

Book a free 20-minute discovery call

Not sure where to start? Feel free to book a call with our team to chat through your objectives. On the call, we’ll talk you through your business goals, asset requirements, processes, expected timelines, and anything else to help you make an informed decision.

What you’ll need to apply

Have these to hand and the application takes a couple of minutes.

  • Your name
  • Phone number
  • Email address
  • Your ABN
  • The type of asset you are financing
  • The price range you are looking at
  • Whether you have a deposit
  • When you need the asset, and how soon

What happens next

  1. 1

    We read your application

    We look at the asset, the amount and your business details.

  2. 2

    We compare lenders

    We shortlist the options that fit and explain them to you.

  3. 3

    We come back to you

    We talk you through what you can do and what it would cost.

  4. 4

    You decide

    Nothing moves forward until you say so.

Frequently Asked Questions

Can I finance a truck that's in another state or regional New South Wales?

Yes. More than half the Sydney deals we place involve a truck outside Sydney, roughly a third interstate and a third in regional New South Wales, and no lender treats that as unusual. What changes is verification: the lender needs to be satisfied the asset exists, matches its description and is free of other claims. We handle that with photographs, a PPSR check and, where it helps, a mechanic's inspection on the ground.

How do I check a truck I have never seen?

We have a network of mechanics we can send to physically inspect the truck before you commit, and you get a written report. That is a qualified person standing next to the asset rather than a seller's photo gallery. Combined with a PPSR search, which uses the VIN or chassis number to show whether money is owed on it or whether it is recorded as written off or stolen, you can buy at a distance with your eyes open.

What does a lender need before it will fund a private sale?

Proof the seller owns the truck, the registration status, a payout figure if there is finance owing, clear photographs of the asset, a PPSR check and usually an inspection. We also ask how and when you plan to get the truck back to Sydney, whether the seller knows the buyer is interstate, and whether they will cooperate with an inspection. Private sales are completely workable. They need one extra layer of proof.

Why do private sale deals get held up?

Photographs, more than anything else. Blurry or partial images mean the lender cannot verify the asset, and chasing a private seller for better ones is slow. The second cause is roadworthiness on older trucks, where work has to be done before the vehicle can be registered, and therefore before settlement. Interstate distance itself is rarely the problem. An uncooperative seller is.

What's involved in registering an interstate truck in New South Wales?

A truck over 4.5 tonnes Gross Vehicle Mass needs a Heavy Vehicle Authorised Inspection Scheme (HVAIS) report. Lighter vehicles need an Authorised Unregistered Vehicle Inspection (AUVIS) report, commonly called a blue slip. Service NSW requires the original report issued no more than 42 days before you lodge, along with proof of identity, proof of registration entitlement, the original number plates and a compulsory third party green slip. Duty may apply, and New South Wales recognises duty already paid in some states.

Can I get finance on a truck that isn't registered?

Often, yes. An unregistered truck cannot settle and be driven away, but it can be pre-approved, and we have structured deals exactly that way. The pre-approval holds the purchase together while registration is sorted, which gives a private seller the confidence to do the work. If the truck you are looking at has lapsed registration, tell us early and we will structure around it.

Can I get pre-approved before I find the truck?

Yes, and for an out of area purchase we would encourage it. Pre-approval tells you what you can spend before you start negotiating, and it lets you tell a private seller you are ready to proceed without qualifying the statement. When the good units sell in days, that is the difference between buying the truck and hearing about the one that got away.

Are you based in Sydney?

Yes. Our core team is in Sydney and we service businesses across Australia. Being here means we know the Sydney market, and it also means we understand why so much of it involves buying somewhere else.

Do you finance owner drivers and small fleets, or only established transport businesses?

Both. We place finance for owner drivers buying their first truck, couriers adding a vehicle to service a new contract, and fleets replacing or expanding. Sole traders and newer ABNs are harder when there is no deposit and no property behind the application, and we will tell you that honestly upfront rather than putting declines on your credit file.

What if the seller wants payment before the inspection is done?

Tell us before you agree to anything. A private seller asking for money ahead of verification is the situation every one of these deals has to avoid, and there is usually a way to structure it so the seller is confident and you are protected. This is precisely where having someone who does this every week is worth more than a slightly sharper rate.

Get a free quote

Step 1 of 2 — Personal Details

Personal details
Your asset and amount
Roughly how much?
Emmanuel Nassar, Co-founder of Stacked Finance

Need help with finance?

Send Emmanuel a message and he’ll get back to you shortly.

Or call Emmanuel directly on 0417 209 702

Send us a message

We'll get back to you shortly.

Apply in 2 simple steps 

No impact on your credit score. Hear back ASAP.

Step 1 of 2 — Personal Details

Personal details
Your asset and amount
Roughly how much?
Emmanuel Nassar, Co-founder of Stacked Finance

Emmanuel

Co-founder

Need help with finance?

Send Emmanuel a message and he’ll get back to you shortly.

By sending this message you agree that we may contact you about your enquiry. Your details are handled in line with our Privacy Policy.


Or call Emmanuel directly on 0417 209 702