Concrete Truck Finance
Finance for agitators, mixers and pump trucks. We know which lenders write this asset and what they check before they say yes.
- 63+ lenders
- 24 hour turnaround
- Servicing all Australia
- Funding as fast as 8 hours
- No doc and low doc available
Excellent reviews from Aussie businesses
A guide to concrete truck finance
Concrete trucks get bought under time pressure. A contract lands, a truck goes down, or a good unit comes up privately and won’t sit around waiting. That’s why the finance conversation is worth having before you find the truck, not after. Stacked Finance concrete truck loan details
Typical Loan Details
- Flexible payment options
- 63+ lenders available
- Weekly, fortnightly, or monthly repayments
- Simple application process
- Borrow up to $500,000
- No deposit available up to $150,000, subject to your profile and the asset
Calculate your estimated concrete truck loan repayments today
Feel free to estimate your rate, term, and deposit to get an idea of how much your repayments might be. Please keep in mind this is only to get a general idea and is not the calculator we will use to determine your actual loan repayments.
$
6.99%
5 years
$495
$29,695
Supporting Australian concrete operators
Concrete is unforgiving on equipment and unforgiving on timing.
You’re running fixed delivery windows, your truck is carrying a perishable product, and a breakdown doesn’t just cost you a day, it costs you the pour and possibly the relationship with the builder.
Meanwhile lenders have been getting more careful with this asset class. Concrete trucks are specialised, they wear faster than general freight equipment, and revenue can be concentrated with a small number of customers. That combination makes some credit teams cautious even when the operator in front of them is running a solid, profitable business.
That’s the gap we work in.
We know which lenders on our panel actually want this asset, which ones will look past an unusual detail, and which ones will waste a week before declining. That knowledge is the difference between a deal that settles this week and three declines sitting on your credit file.
Whether you’re an owner-operator buying your first agitator, a supplier expanding a delivery fleet, or you’re taking over an existing Lorry Owner Driver operation, we’ll tell you honestly what’s placeable before we put anything on your credit file.
Your options at a glance
Finance structures compared
| Structure | Ownership | Tax treatment | Balloon | Best for |
|---|---|---|---|---|
| Chattel mortgage | You own the asset from day one; the lender holds a mortgage over it as security. | GST, depreciation and interest are generally deductible. Speak to your accountant. | Available | Businesses that want to own the asset from the start. |
| Finance lease | The lender owns the asset during the term; you have full use of it. | Payments may be deductible depending on your circumstances and business use. Speak to your accountant. | Residual payment to take ownership | Businesses that want to use the asset now and buy it at the end. |
| Commercial hire purchase | The lender owns the asset during the term; ownership transfers to you at the end. | GST, interest and depreciation are generally deductible. Speak to your accountant. | Available (final instalment) | Businesses that want to own the asset later, paid off in instalments. |
| Operating / rental lease | You never own the asset. You use it and return it at the end. | Payments may be deductible as an operating expense. Speak to your accountant. | Not applicable (you return the asset) | Short-term needs, or businesses that upgrade equipment often. |
What we need from you
| Item | Why we need it |
|---|---|
| Your name and contact details | So we can reach you and talk through the right option for your business. |
| Your ABN | So we can confirm you're financing through the business and match you with commercial lenders. |
| The asset type and price range | So we know which lenders actually fund that asset, and whether it's a no doc, low doc, or full doc application. |
| Whether you have a deposit, and when you need the asset | So we can structure the repayments around your cash flow and the date you need it. |
Get in touch with our team of Asset Finance Brokers today.
You can book a free discovery call with our team to learn about your options or simply submit an enquiry and we’ll call you back as soon as possible.
What are the pros and cons of a concrete truck loan?
Cons
- Concrete trucks depreciate faster than general freight equipment
- Drum and barrel maintenance is an ongoing cost most operators underestimate
- Fewer lenders write this asset, so the panel is narrower than for a standard truck
- Older units hit the 25 year end-of-term ceiling quickly
- Revenue concentration with one or two customers makes some credit teams nervous
- Insurance obligations can be heavier, particularly where the mixer is supplied under contract
- Fixed repayments continue through seasonal slowdowns and wet weather
- Specialised resale market means selling takes longer if you need to exit
Pros
- Own the truck outright from day one with a chattel mortgage
- No deposit available up to $150,000, subject to your profile
- GST, depreciation and interest treatment that generally works in your favour
- Take on new supply contracts without tying up working capital
- Balloon payment options can reduce monthly repayments
- Builds real equity in an asset your business runs on
- Pre-approval lets you move fast on a private sale
- Drum and chassis can sometimes be financed separately depending on the scenario
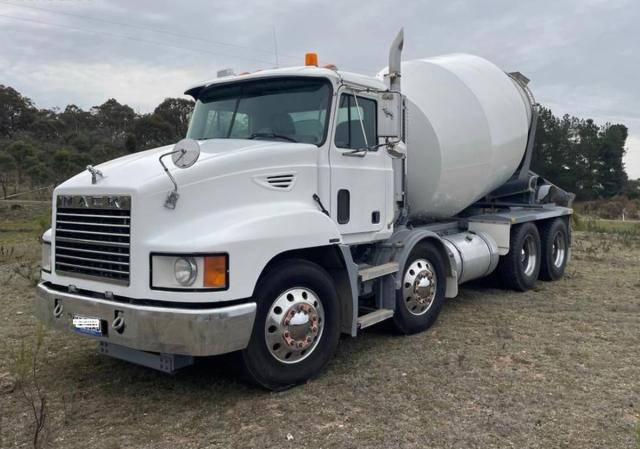
Concrete Supplier
- 2005 Mack Metro Liner agitator, 471,000km
- Private sale, unregistered, at the edge of lender age limits
- Pre-approved before rego, settled once it came through
A concrete supplier in New South Wales came to us wanting a 2005 Mack Metro Liner agitator with around 471,000 kilometres on it.
Two problems. The truck was old enough to sit right at the edge of what lenders will touch. And it wasn’t registered, which meant it couldn’t settle in the state it was in.
It was a private sale, so there was no dealer holding the truck for anyone.
We took it to a lender on our panel who understood the asset and the condition it was in, and secured pre-approval before registration was sorted. That pre-approval is what held the deal together. It gave the seller the confidence to go and get the truck registered, knowing the buyer was funded and the sale was real.
Once rego came through, the deal settled and the truck went to work.
The detail worth taking from this: an unregistered truck can’t settle, but it can absolutely be pre-approved. If you’re looking at a private sale and the rego has lapsed, that’s not the end of the conversation. It’s the start of a different one.
Our process
Learn about you
A discovery call to understand your business and your concrete truck requirements.
Compare concrete truck loans
We shortlist the most favourable options and explain each one.
Get pre-approved
Pre-approval based on steps 1 and 2, so you can move on a truck with confidence.
Secure your truck
Found it? We make sure you’re approved and the funds are there.
Why choose Stacked Finance?
Australia Wide
Our core team is based in Sydney. However, we support businesses all over Australia including Melbourne, Brisbane, Perth, Adelaide, Gold Coast, Canberra, and Newcastle.
Trustworthy
We believe integrity is the most important quality of a broker. Our team is honest and transparent about the options, fees, rates, timelines, and anything else you need to know.
24/7 Support
We’re committed to helping our clients. This means being available when they are. Most of our clients are busy running their companies – we ensure we’re available to support you when you need it most.
Let's talk loan details
- Up to $500,000
- Secured and unsecured
- 3, 5, and 7 years (depending on the age of the asset)
- Weekly, fortnightly, and monthly
- Fixed
- No deposit available up to $150,000, subject to your profile and the asset
- Generally up to 25 years at the end of the loan term
We have access to 63+ lenders and we're adding more
Book a free 20-minute discovery call
Not sure where to start? Feel free to book a call with our team to chat through your objectives. On the call, we’ll talk you through your business goals, asset requirements, processes, expected timelines, and anything else to help you make an informed decision.
What you’ll need to apply
Have these to hand and the application takes a couple of minutes.
- Your name
- Phone number
- Email address
- Your ABN
- The type of asset you are financing
- The price range you are looking at
- Whether you have a deposit
- When you need the asset, and how soon
What happens next
We read your application
We look at the asset, the amount and your business details.
We compare lenders
We shortlist the options that fit and explain them to you.
We come back to you
We talk you through what you can do and what it would cost.
You decide
Nothing moves forward until you say so.
Frequently Asked Questions
What is concrete truck finance?
Concrete truck finance is a commercial loan that lets your business acquire an agitator, mixer or pump truck without paying the full amount upfront. You repay it in regular instalments across an agreed term, usually three to seven years, and in most structures you own the truck from day one.
Which types of concrete trucks do you finance?
Agitators and mixer trucks, concrete pump trucks, boom pumps, line pumps and volumetric mixers. New and used. We can also look at the drum or body separately from the cab chassis depending on the scenario, which comes up regularly for operators who already own a chassis.
How old a concrete truck can I finance?
Generally the asset needs to be no more than 25 years old at the end of the loan term, not at the time of purchase. So a 2005 truck on a five year term is right at the limit. Older assets can sometimes still be placed with the right lender, deposit and business profile, but the panel narrows considerably.
Can I finance an unregistered concrete truck?
An unregistered truck can’t settle, but it can be pre-approved. We’ve done exactly this on a private sale where the seller needed to sort registration. The pre-approval held the deal together while it happened. If you’re looking at an unregistered truck, tell us early and we’ll structure around it.
Do I need a deposit?
Not always. We have no deposit options up to $150,000, subject to your profile and the asset. That said, a deposit meaningfully widens the panel, particularly on older trucks or where trading history is short. If you’ve been operating under six months, aren’t property backed and can’t put a deposit down, that combination is genuinely hard to place and we’ll tell you upfront.
Can I get concrete truck finance with a low doc application?
Yes. Low doc works well when you can offer a deposit or you’re property backed. One or the other usually needs to be there, because the lender has to hedge somewhere. Without either, a low doc application on a specialised asset becomes difficult.
Can I finance a concrete truck as a sole trader?
Yes. Sole traders and owner-operators finance concrete trucks regularly. Terms are usually better if you have property or another unencumbered asset behind you, and the tax treatment differs from a company structure, so it’s worth a conversation with your accountant.
What about buying an existing Lorry Owner Driver operation?
We can look at it. Taking over an existing LOD operation, where you’re buying the truck and stepping into the contract, is a different application to simply buying a truck, because the value sits partly in the arrangement itself. Bring us the details and we’ll work out how it’s best structured.
Can I still get finance with a bad credit score?
Often, yes. A poor credit history doesn’t automatically rule you out, though it does narrow the panel and generally means less favourable terms. What helps most is a strong asset and either a deposit or property behind you. Book a call and we’ll tell you honestly where you stand.
What’s the process for buying from a private seller?
Private sales are common on concrete trucks and completely workable. The lender will usually want proof of the seller’s identity, proof of ownership, photo verification of the VIN, engine number, plates and condition, and sometimes a mechanical inspection. It adds a step. It doesn’t add a problem.
Do I need insurance?
Yes. Comprehensive cover is effectively mandatory and most lenders require proof of it before settlement. If you’re operating under a supply contract, check the contract carefully, because some arrangements carry specific insurance obligations including public liability extensions for agitator damage.
What other services do you offer?
Stacked Finance works with Australian businesses across commercial asset and business finance. That includes truck finance, equipment finance, trailer finance and agricultural finance, as well as working capital, cash flow and unsecured business lending. We’re commercial only.
Need help with finance?
Send Emmanuel a message and he’ll get back to you shortly.
Or call Emmanuel directly on 0417 209 702