Quick & Easy Trailer Finance for Aussie Businesses
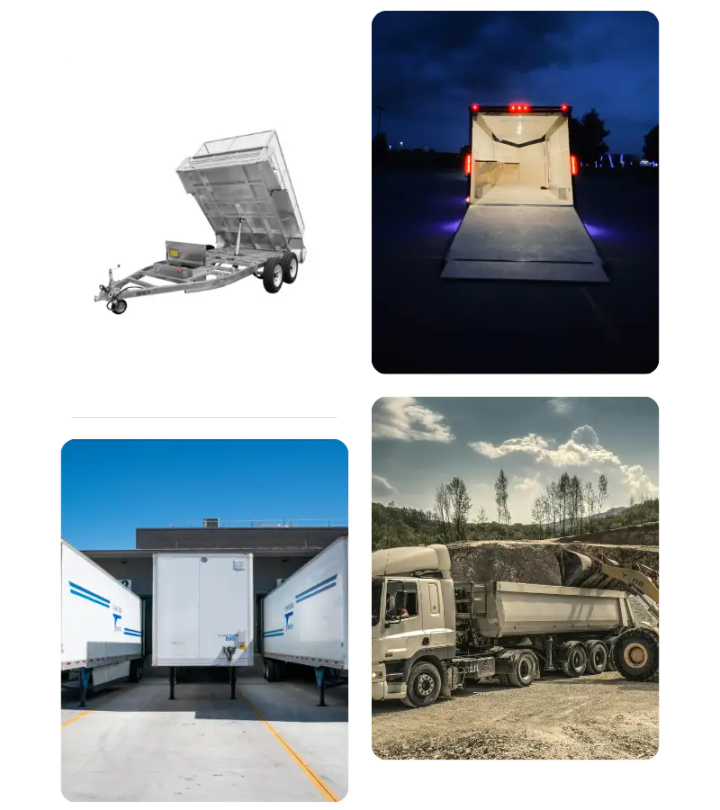
Whether you’re looking for a fleet of semi-trailers or need a small galvanised hydraulic tipper trailer, our team will make it happen. We help Aussie businesses get the trailers they need in less than 24 hours.
- 63+ lenders
- Priority Service
- 24 hour turnaround
- Funding as fast as 8 hours
- Commercial trailer finance
- No doc and low doc available
- Financing hundreds of trailers
A quick guide to trailer finance
Whether you’re hauling livestock, shifting machinery, or simply needing a tipper for your construction sites our team will make it happen. Every finance solution is tailored to match your business needs, industry requirements, and business circumstances. Asset finance is essential for Australian businesses across every industry. Here’s an overview of our finance options. Please note that terms and rates may vary at the time of application based on market conditions and individual assessments.
Typical Loan Details
- 7yr Loan Terms Available
- 63+ lenders available
- Weekly, fortnightly, or monthly repayments
- Borrow up to $500k with a low doc loan
- Early repayments options
- Balloon payment options
- No deposit (even for non home owner)
- Trailers across all industries in Australia
Calculate your estimated trailer loan repayments today
Feel free to estimate your rate, term, and deposit to get an idea of how much your repayments might be. Please keep in mind this is only to get a general idea and is not the calculator we will use to determine your actual loan repayments.
$495
$29,695
Trailer loans for your needs
Securing the right trailer is a big deal and can make or break your business. Our job is to cut through the noise, find you the right trailer loan, and close a deal quickly.
We work with local Aussie businesses just like yours. Whether you’re a tradie expanding your fleet, a transport company signing new routes, or a small business looking to upgrade your box trailers, we’re here to make it happen.
Our team understands how important it is to ensure you get the best service possible, access to the right finance, and support throughout the whole process.
Unlike a home loan or personal loan, your access to equipment & trailers finance will determine how fast you can grow your business.
Get in touch with our team today so we can guide you through the process and find the best deal on your trailer!
Your options at a glance
Finance structures compared
| Structure | Ownership | Tax treatment | Balloon | Best for |
|---|---|---|---|---|
| Chattel mortgage | You own the asset from day one; the lender holds a mortgage over it as security. | GST, depreciation and interest are generally deductible. Speak to your accountant. | Available | Businesses that want to own the asset from the start. |
| Finance lease | The lender owns the asset during the term; you have full use of it. | Payments may be deductible depending on your circumstances and business use. Speak to your accountant. | Residual payment to take ownership | Businesses that want to use the asset now and buy it at the end. |
| Commercial hire purchase | The lender owns the asset during the term; ownership transfers to you at the end. | GST, interest and depreciation are generally deductible. Speak to your accountant. | Available (final instalment) | Businesses that want to own the asset later, paid off in instalments. |
| Operating / rental lease | You never own the asset. You use it and return it at the end. | Payments may be deductible as an operating expense. Speak to your accountant. | Not applicable (you return the asset) | Short-term needs, or businesses that upgrade equipment often. |
What we need from you
| Item | Why we need it |
|---|---|
| Your name and contact details | So we can reach you and talk through the right option for your business. |
| Your ABN | So we can confirm you're financing through the business and match you with commercial lenders. |
| The asset type and price range | So we know which lenders actually fund that asset, and whether it's a no doc, low doc, or full doc application. |
| Whether you have a deposit, and when you need the asset | So we can structure the repayments around your cash flow and the date you need it. |
Get in touch with our team of Asset Finance Brokers today.
You can book a free discovery call with our team to learn about your options or simply submit an enquiry and we’ll call you back as soon as possible.
What are the pros and cons of a trailer loan?
Cons
- Higher monthly repayments
- Paying in cash will save you interest
- Can still tie up some working capital
- Requires a good credit history for a good rate
- Insurance costs can be slightly higher
- Risk of negative equity if the equipment value drops
- Long-term commitment
- Easy to overcommit to new business
Pros
- Can own the trailer outright from day one
- No deposit required (even for non-home owners)
- Tax benefits (GST, depreciation, interest, etc)
- Builds business equity
- Possible balloon payment option to lower repayments
- Can grow the business without tying up capital
- Take on new customers or contracts faster
- Easier to forecast business growth and requirements
- Can access discounts through brokers
Our process
Learn about you
We offer discovery calls to learn about your business & trailer finance requirements.
Compare loans
We’ll shortlist the best options for your trailer loan and explain them to you.
Get pre-approved
We’ll secure pre-approval based on steps 1 and 2 so you have peace of mind.
Secure your asset
Found the trailer you need? We’ll make sure you’re approved and the funds are available.
Why choose Stacked Finance?
Australia Wide
Our core team is based in Sydney. However, we support businesses all over Australia including Melbourne, Brisbane, Perth, Adelaide, Gold Coast, Canberra, and Newcastle.
Trustworthy
We believe integrity is the most important quality of a broker. Our team is honest and transparent about the options, fees, rates, timelines, and anything else you need to know.
24/7 Support
We’re committed to helping our clients. This means being available when they are. Most of our clients are busy running their companies – we ensure we’re available to support you when you need it most.
Let's talk loan details
- Up to $500,000
- Secured and unsecured
- 3, 5, and 7 years (depending on the age of the asset)
- Weekly, fortnightly, and monthly
- Fixed
- No deposit available up to $150,000, subject to your profile and the asset
- Generally up to 25 years at the end of the loan term
Some of our lenders on panel (we have access to 63+ lenders)
Book a free 20-minute discovery call
Not sure where to start? Feel free to book a call with our team to chat through your objectives. On the call, we’ll talk you through your business goals, asset requirements, processes, expected timelines, and anything else to help you make an informed decision.
What you’ll need to apply
Have these to hand and the application takes a couple of minutes.
- Your name
- Phone number
- Email address
- Your ABN
- The type of asset you are financing
- The price range you are looking at
- Whether you have a deposit
- When you need the asset, and how soon
What happens next
We read your application
We look at the asset, the amount and your business details.
We compare lenders
We shortlist the options that fit and explain them to you.
We come back to you
We talk you through what you can do and what it would cost.
You decide
Nothing moves forward until you say so.
Frequently Asked Questions
Am I eligible for a trailer loan?
Most Australian businesses (including sole traders) are eligible for trailer finance!
We typically look for established businesses with a solid trading history, decent cash flow, and a clear plan for how the asset will increase your business performance. Lenders also need two years of ABN and GST registration to be eligible for most low-doc and no-doc loans.
Whether you’re a small tradie in Perth or a growing SME in Sydney, we’ll find a financing solution that fits.
How fast can I get a trailer loan?
Our process is designed for business owners who need things done quickly. Depending on your loan type, documentation, and asset type, we can turn around an approval in 24-48 hours. Once approved, funds can be released within a couple of hours.
Which equipment finance terms should I know?
When it comes to trailer finance (or equipment finance in general) there are many terms to learn. Each of them is important in its own way and to some degree is essential if you plan on getting a trailer loan for your business. Here are the top terms we suggest getting your head around:
- Chattel mortgage – A loan that is secured by the asset you purchase.
- Operating lease – An arrangement where you rent the equipment but don’t own it.
- Finance lease – Where you can lease the asset with the option to purchase at the end of the term.
- Commercial hire purchase – Pay for the asset in installments and own it later.
- No doc loan – Close to zero financial documentation is required for this loan.
- Low doc loan – Minimal paperwork for getting a loan.
- Full doc loan – Detailed financials are required by lenders to access better terms.
- Residual value – The estimated worth of your asset after it has fully depreciated.
- Balloon payment – A large payment at the end of the loan term.
- Depreciation benefits – Tax deductions for the asset use.
- Loan Principal – The original amount borrowed.
- Credit Score – Your rating of financial trustworthiness by credit companies.
- Lender Criteria – The lender rules to qualify for finance.
- GST – 10% tax applied to the purchase price.
- Tax deductibility – Your claimable expenses for financing.
- Asset turnover ratio – The measure of revenue from assets.
- Credit assessment – The lender’s evaluation of your borrowing capacity.
- Fixed interest rate – The fixed interest rate that does not fluctuate with the market.
- Variable interest rate – The interest rate that fluctuates with the market.
- Broker fee – Our fee for arranging the finance deal.
- Early termination fee – A penalty for paying off your loan early.
- Bank statements – your bank transactions to confirm you can afford the repayments.
But don’t worry! There’s no need to remember all of this.
Our team of asset finance brokers is here to make this process quick, simple, and easy for you.
Which types of trailers can I finance with Stacked Finance?
At Stacked Finance, we understand that commercial finance has a golden rule: assets must serve a clear business purpose.
Lenders have specific criteria about what qualifies.
They’re looking at the asset’s potential to generate value for your business.
In addition, most lenders have stringent policies about the types of assets they’ll finance based on resale value. These are usually categorised as primary, secondary, or tertiary (in some cases category A, B, or C). We take a comprehensive approach to trailer financing, ensuring we meet these critical commercial criteria.
Our financing solutions span a wide range of trailer types across Australia, supporting farmers, tradies, and other businesses:
Our finance solutions span a wide range of trailer types across Australia including:
- Tractor trailers – Designed to support farming and heavy-duty agricultural operations
- Horse and livestock trailers – Supporting farmers and horse lovers carting their four-legged mates
- Log trailers – Tailored for forestry and timber transport businesses
- Cargo trailers – Perfect for businesses and tradies needing to move gear securely
- Tipping trailers – Essential for construction, landscaping, and agricultural crews
- Car carrier trailers – Ideal for automotive businesses and motorsport teams shifting vehicles
- Side tipper trailers – Specialised equipment for efficient material handling
- Boat trailers – Helping marine businesses get their watercraft where they need to go
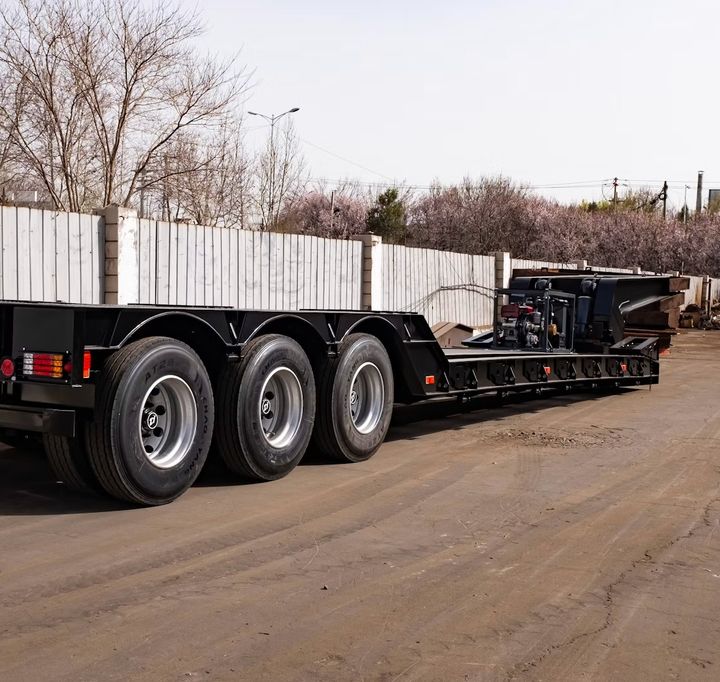
- Semi truck trailers – Comprehensive solutions for commercial trucking
- Tradesman trailers – Supporting tradies with mobile workshop and equipment transport options
- Flatbed trailers – Great all-rounder for any type of equipment including an ATV or car.
We finance both brand new and second-hand trailers, giving you the flexibility to match your budget and specific requirements.
Our team is ready to help you find the right financing solution for your trailer needs, ensuring your assets work as hard as you do.
Can I finance a trailer if I’m a sole trader?
Getting trailer finance is pretty simple and common in Australia. Trailer loans generally use the trailer itself as security, which benefits both the lender and the business owner. The process typically involves three key structures in the Australian market:
Chattel Mortgage
- Most common for businesses purchasing trailers they intend to own
- You borrow funds to purchase the trailer
- The trailer serves as collateral for the loan (like a normal mortgage for a house)
- Tax benefits include potential GST input credits and depreciation claims
- Ownership transfers to you immediately upon purchase so the trailer is on your balance sheet
Finance Lease
- Ideal for businesses that want flexibility and lower upfront costs
- The lender purchases the trailer and leases it to your business
- Usually shows on the balance sheet as well
- Regular fixed payments over an agreed term
- At term’s end, you can either purchase the trailer, return it, or refinance to a new lease
Hire Purchase
- Similar to a secured loan
- You agree to purchase the trailer over time through installments
- Trailer ownership transfers to you at the end of the term
- Typically used for trailers with predictable value and lifespan
Most businesses opt for one of the above methods because it has the following benefits:
- Preserves working capital
- Potential tax advantages
- Faster equipment acquisition
- Predictable budgeting through fixed repayments
- Flexible structure to match business cash flow
- ATO recognises these structures and allows potential tax deductions and GST benefits
How does trailer finance work in Australia?
Getting trailer finance is pretty simple and common in Australia. Trailer loans generally use the trailer itself as security, which benefits both the lender and the business owner. The process typically involves three key structures in the Australian market:
Chattel Mortgage
- Most common for businesses purchasing trailers they intend to own
- You borrow funds to purchase the trailer
- The trailer serves as collateral for the loan (like a normal mortgage for a house)
- Tax benefits include potential GST input credits and depreciation claims
- Ownership transfers to you immediately upon purchase so the trailer is on your balance sheet
Finance Lease
- Ideal for businesses that want flexibility and lower upfront costs
- The lender purchases the trailer and leases it to your business
- Usually shows on the balance sheet as well
- Regular fixed payments over an agreed term
- At term’s end, you can either purchase the trailer, return it, or refinance to a new lease
Hire Purchase
- Similar to a secured loan
- You agree to purchase the trailer over time through installments
- Trailer ownership transfers to you at the end of the term
- Typically used for trailers with predictable value and lifespan
Most businesses opt for one of the above methods because it has the following benefits:
- Preserves working capital
- Potential tax advantages
- Faster equipment acquisition
- Predictable budgeting through fixed repayments
- Flexible structure to match business cash flow
- ATO recognises these structures and allows potential tax deductions and GST benefits
How can I get the lowest repayments for my trailer loan?
Reducing your repayments on a trailer loan comes down to a few core factors. Here’s what we recommend to our clients to keep costs low:
Loan term strategies
- Extend the trailer loan term (more months = smaller repayments)
- Balance term length against total interest paid
- Consider 5-7 year terms for optimal flexibility
Deposit & upfront payment
- A larger initial deposit will always reduce the principal & interest
- Lower borrowing amount means smaller monthly repayments
- Aim for 20-30% deposit if possible since you’ll also access lower rates (lenders like deposits)
Additional Tactics
- Choose a trailer with a strong resale value (Category A or Primary Assets have better rates)
- Negotiate trailer pricing before financing (our team can help source your trailer as well)
- Consider residual payment structures (i.e. balloon payments)
- Compare multiple lender options
- Consider a full-documentation loan to access a better rate
Pro Tip: Don’t just chase the lowest repayment. The cheapest option isn’t always the most cost-effective long-term. A slightly higher repayment might save you thousands in total interest.
Our brokers will crunch the numbers and find a sweet spot between repayment size and overall loan cost.
Should I get a trailer loan or should I buy the trailer in cash?
Unfortunately, we can’t offer financial advice, so this is something you will need to discuss with your accountant. However, here are some things to consider about getting a trailer loan:
- You will retain a lot of working capital which is critical for a business
- There are often tax advantages associated with an asset loan
- The faster you can acquire the asset the faster it can earn income
P.S. If a trailer loan isn’t right for you consider a payment plan with the trailer manufacturer. These may not be available for every make and model but they could help you access the trailer quickly.
What other services do you offer?
Stacked Finance primarily focuses on the commercial market as opposed to the consumer.
This means we only help Australian businesses obtain asset loans or business loans.
Whether you need a new asset like a vehicle, trailer, truck, or equipment, we can help. Our team is also skilled at providing working capital loans, cash flow finance, unsecured loans, startup loans, or any other specific type of business-related funding.
Need help with finance?
Send Emmanuel a message and he’ll get back to you shortly.
Or call Emmanuel directly on 0417 209 702