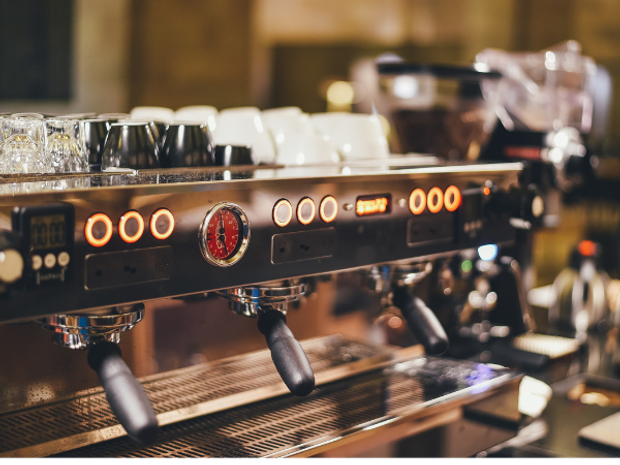
Perth Café
Approved and settled with no deposit
Hospitality equipment, a smaller lender pool than yellow goods
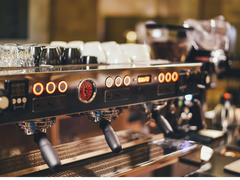
3 Group Commercial espresso machine, $24,000
Excavators, cranes, workshop gear, utes and fit-outs for businesses across Perth and Western Australia. One application, 63+ lenders, and an answer in about fifteen minutes.
Some of the lenders we have on panel
Almost anything a business uses to earn, as long as it is commercial. We do not write consumer lending.
In practice that means yellow goods and civil plant, workshop and fabrication equipment, utes and light commercial fleets, trailers and transport gear, hospitality and medical fit-outs, IT and point-of-sale, agricultural machinery, and the one-off specialised item that no generic lender has a category for.
The reason it is worth going through a broker rather than your own bank is lender fit. An excavator and a commercial espresso machine are both equipment, but they sit in different categories with different lender pools, different age limits and different appetites. A Perth café we funded recently bought a three-group commercial machine with no deposit, hospitality gear sits in a secondary category where the machine holds value while it is serviced, but far fewer lenders write it than write an excavator. Knowing which ones do is most of the job.
A lot of equipment finance in this state ultimately traces back to resources, not the miners themselves so much as the contractors around them.
Earthmoving and civil plant for site works, crushing and screening gear, lighting towers, generators, water carts, service trucks and workshop equipment at a depot in Welshpool or Kwinana supporting machines out in the Pilbara or the Goldfields.
The work is contract-shaped, and so is the income. That shape is the problem a bank template has, and it is not really a credit problem at all.
Income that arrives against contract milestones looks lumpy on a bank statement. Assessed by a lender who writes civil contracting every week, the same statements read as a contract with a start and an end.
We place those files accordingly, and we match the term to the contract rather than defaulting to five years because five is the default.
Swipe for more reviews →
Daniel Sutarov
I couldn't recommend Emmanuel enough. Fast, professional and goes the extra mile. Even to the point of driving over an hour away to sort out the final bit of finance. Absolute machine. Thank you very much for everything.
An Nguyen
Luke and his team was amazing and swift throughout the finance/purchasing of our new business Ute. Highly recommended!!
Sofia Martinez
I had such a great experience working with Emmanuel and Luciano. They made the whole process of securing finance super smooth and stress free. Communication was always clear and they went above and beyond to make sure I understood every step. Thanks to their help, I was able to secure the right funding to scale my business with confidence. Really appreciated their honesty, support and genuine care throughout the process. Highly recommend to anyone looking for a broker who actually has your best interest. Thanks guys.
Steve
Wonderful to deal with and extremely helpful in getting me the finance I needed for my business needs. I highly recommend Emmanuel.
Kevin Tran
Emmanuel and his team were very professional and responsive with our enquiries and helped me get much needed equipment, will definitely recommend to friends and family. Keep up the great work mate
Leeor Meirovitz
Can’t recommend the team at Stacked Finance enough. I was looking for a reliable asset finance broker in Sydney to help expand our fleet, and they made the whole process incredibly smooth. Unlike other brokers I’ve dealt with, they moved fast and understood exactly what my business needed without the usual back-and-forth. They secured a great rate on our new truck and handled all the heavy lifting. If you need professional asset finance services for trucks or equipment, these are the guys to call. 10/10 service.
Irene Nour
Emmanuel and Luciano from Stacked Finance went above and beyond and secured the best finace deal for me. They took the time to understand my needs, guided me through every step, and secured a great finance option quickly. Their professionalism and friendly approach made the whole experience a pleasure. I highly recommended!
Ivan Toma
The team was very helpful in helping with the finance for second hand box truck. Highly recommended
Smaller than the mining files and much more common: a fabricator buying a press brake, a mechanic fitting out a second hoist bay, a cabinet maker upgrading a CNC router, a landscaper adding a mini excavator and a tipper trailer.
These usually come down to how much paperwork you want to produce. A full doc application with tax returns and financials gets the sharpest terms available to you. A low doc application works off bank statements and your trading position, which suits a business whose last lodged year does not look like the business does now.
Structure is normally a chattel mortgage, you own the equipment from day one, the lender takes security over it, or a commercial hire purchase, where ownership transfers at the end. The choice is mostly an accounting one. That is the question for your accountant, not for us.
Most of the gear we fund in this state lives in a handful of places: Welshpool and Canning Vale, Malaga and Wangara to the north, Bibra Lake and Henderson down towards the coast, and the Kwinana strip. Fremantle pulls freight and logistics equipment around it the way any working port does.
Different corridors, broadly the same finance question.
Forklifts and materials handling, racking and warehouse fit-out, light commercial fleets running between depots, workshop plant, compressors, and the trailers that move all of it. None of it is exotic. What varies is whether the item has a resale market, because that is what decides how much of the purchase a lender will fund and on what terms.
Perth buys further from home than anywhere else in the country, and on specialised gear there is often nothing suitable in the state at all.
A private sale works the same way as it does for a truck. The lender pays the seller directly, we run a PPSR check to make sure nothing is owing against the machine, and funds do not move until the title is clean. On used equipment we arrange an independent inspection with a written report before you commit, which protects you and satisfies the lender at the same time.
The two things that slow these deals down are always the same.
Serial plate, hour meter, overall condition. Vague photos come straight back and the round trip costs days.
Freighting a machine across the Nullarbor is a real number and it is better in the plan than discovered after settlement.
If you are financing plant that travels on a public road under its own power or on a float, Western Australia's Restricted Access Vehicle rules are worth understanding before you buy. Main Roads WA regulates RAVs in three classes and every combination operates under a Main Roads permit or order. For plant and machinery, Class 1 is the one that matters.
Class 1 covers a vehicle that exceeds a prescribed mass or dimension limit and is a special purpose vehicle, an agricultural machine or implement, or is carrying a large indivisible item. In practice that is a long list of things a civil contractor buys.
Road trains, B-doubles and vehicles carrying multi-modal freight containers are specifically excluded from Class 1, they fall into the other two classes.
None of this changes how a lender assesses you. It changes what the machine can legally do once you own it, which is worth settling before the money moves rather than after. If the asset you are financing is a truck or a road train combination rather than plant, the full class breakdown is on our truck finance in Perth page.
Financing equipment in Perth comes down to three routes, and they differ in ways that decide the outcome rather than just the rate.
Scroll the table sideways →
| Route | Specialist broker | Major bank | Dealer or vendor finance |
|---|---|---|---|
| Who they lend to | Sole traders, contractors, small fleets and established businesses | Established businesses with clean financials and newer assets | Buyers of that supplier's own equipment |
| How income is assessed | Full doc, low doc or no doc, whichever fits your paperwork | Full doc as standard: tax returns, financials, BAS | Limited assessment, geared to closing the sale |
| Lender choice | 63+ lenders, so the asset and the profile pick the lender | One lender, one policy | Usually one financier tied to the supplier |
| Used and private sale | Funds used and private sale, including older and specialised gear | Prefers new or near-new from a dealer | Only that supplier's stock |
| Unusual assets | Placed with a lender who writes that category | Often declined for having no category | Not applicable |
| Pre-approval speed | Pre-approved before you commit, so you can move when the machine appears | You apply once you have found the asset, then wait | Decided at the point of sale, for that supplier only |
Move the sliders for a rough monthly figure. It is a planning estimate, not an offer, your actual terms depend on the asset, the structure and your profile.
Monthly Repayment
$497
Estimate only. Not a quote or an offer of finance.
Perth businesses buy more of their equipment from outside the state than anyone else, which puts the weight on pre-approval, inspection and getting transport into the numbers early.
TYPICAL LOAN DETAILS
Submit an enquiry and we’ll call you back as soon as possible.
Perth Café
Hospitality equipment, a smaller lender pool than yellow goods
3 Group Commercial espresso machine, $24,000
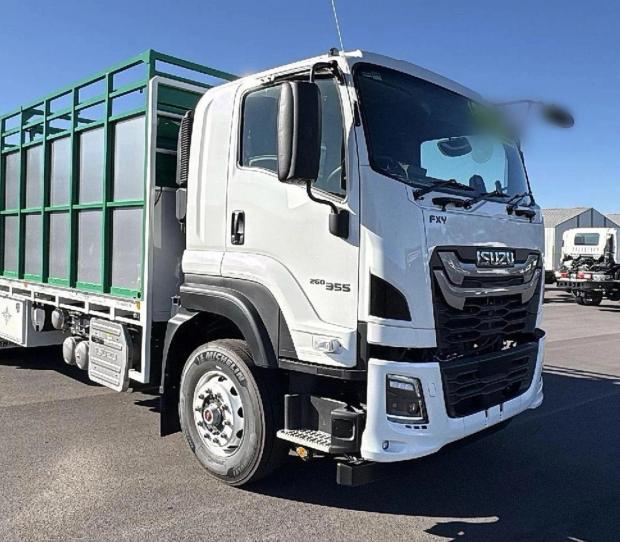
Livestock transport
No deposit, truck and trailer together, waiting on details to come through
2025 Isuzu FXY 260-355 with cattle crate and livestock trailer
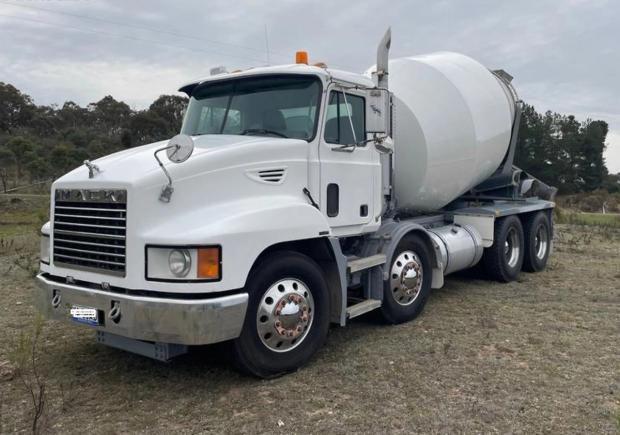
Concrete Supplier
Private sale, unregistered, at the edge of lender age limits
2005 Mack Metro Liner agitator, 471,000km
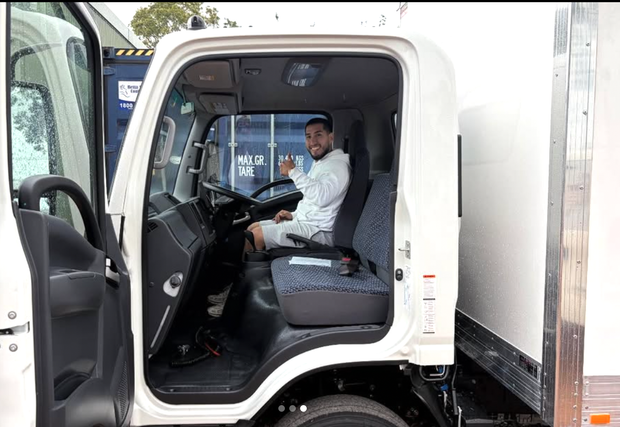
Courier Business
New delivery contract, truck needed fast, bought in Newcastle, dealer finance slow
2024 Isuzu Pantech
What the business does, what the equipment is for, and what your paperwork looks like.
Different assets sit with different lenders. We take the file to the ones who write yours.
Approval before you commit, so you can move when the right machine comes up.
Inspection, PPSR, payment direct to the seller, and the equipment is yours.
ABOUT STACKED FINANCE
Our core team is based in Sydney. However, we support businesses all over Australia including Melbourne, Brisbane, Perth, Adelaide, Gold Coast, Canberra, and Newcastle.
We believe integrity is the most important quality of a broker. Our team is honest and transparent about the options, fees, rates, timelines, and anything else you need to know.
We’re committed to helping our clients. This means being available when they are. Most of our clients are busy running their companies – we ensure we’re available to support you when you need it most.
Civil and earthmoving plant, workshop and fabrication machinery, forklifts and materials handling, utes and light commercial fleets, trailers, hospitality and medical fit-outs, IT and point-of-sale systems, and agricultural machinery. If an item has a resale market and the purchase is commercial, there is almost always a lender for it. We do not write consumer lending.
Not always. No deposit is available up to $150,000, subject to your profile and the asset. Above that, a deposit usually enters the conversation, though the equipment itself carries a lot of the security. The deciding factors are the asset type, its age and your trading history, so it is worth asking before assuming you need to save first.
Yes, including private sales. On used gear the lender pays the seller directly, we run a PPSR check to confirm nothing is owing against the machine, and we arrange an independent inspection with a written report before you commit. Age limits vary widely between lenders, which is exactly why the lender is chosen to suit the asset rather than the other way round.
An approval can land within 24 hours on a clean file and funding has gone through in as little as eight hours. For a Perth purchase the realistic timeline usually depends on the asset rather than the finance, a used machine interstate needs an inspection and a PPSR check first, and transport across the Nullarbor needs booking. Pre-approval first keeps everything after it short.
Under a chattel mortgage you own the equipment from day one and the lender registers security over it. Under a commercial hire purchase, ownership passes to you at the end of the term. For most businesses the practical difference is an accounting one rather than a cashflow one, so it is a question for your accountant.
Often yes. A short history narrows the lender pool rather than closing it, and the lenders who write newer ABNs are a different set from the majors. A low doc application assessed on bank statements and the work in front of you is the usual route. The asset itself matters here too: equipment with a strong resale market is easier to fund than something specialised.
Yes. Hospitality, medical, dental and retail fit-outs are all financeable, though they sit in a different category from yellow goods because a fit-out is harder to recover and resell. That means a smaller lender pool and a different assessment, not a closed door. We place these with financiers who write the category regularly.
Not the assessment, but it affects what you can do with the machine. Western Australia regulates Restricted Access Vehicles through Main Roads WA in three classes, and plant such as cranes, concrete pump trucks, graders, low loaders and jinkers falls under Class 1 when it exceeds a prescribed mass or dimension limit. Every combination runs under a Main Roads permit or order.
Yes, and for Perth businesses it is routine rather than unusual, because specialised gear often does not exist in the state. The process is the same as a local purchase with two additions: an independent inspection on used equipment, and freight costed into the deal from the start rather than discovered after settlement.
No. Property can widen the lender pool on a larger purchase, but it is not a requirement and plenty of the businesses we fund are not property owners. The equipment is the security. Where property helps most is on higher amounts or on assets with a thinner resale market.
Yes. Weekly, fortnightly and monthly are all standard, and seasonal structures are available for businesses whose income arrives in cycles rather than evenly, common for agricultural machinery and for contractors working to shutdown schedules. It has to be arranged at the start rather than renegotiated later, so raise it in the first conversation.
Yes. Multiple assets can go on one facility or be split across lenders where that produces a better result, which is common when a contractor buys a machine and the float to move it. Splitting is sometimes the sharper outcome because the two assets suit different lenders, and that is a decision we make per deal rather than by rule.
Some lenders do, and specialised gear often has to come in from overseas. Talk to us before you pay the supplier a deposit.
Yes. A machine you own outright can be refinanced to free up capital. Contractors use it to fund a float, or a second machine, without touching the overdraft.
Send us a message or call directly on 0417 209 702

